Eclipse Energy Converts Depleted Wells into Cheap Hydrogen Factories
Producing clean hydrogen at $0.56 per kilogram sounds like a promise too good to be true for the current moment in the energy sector. To put it in perspective: green hydrogen produced through electrolysis costs between four and seven times more. Conventional hydrogen, derived from natural gas, costs at least three times as much. If Eclipse Energy can prove that its figures hold up beyond a thirty-day pilot project in the Permian Basin of Texas, we would not be looking at a marginal optimization of the hydrogen market. We would be looking at a complete restructuring of its cost architecture.
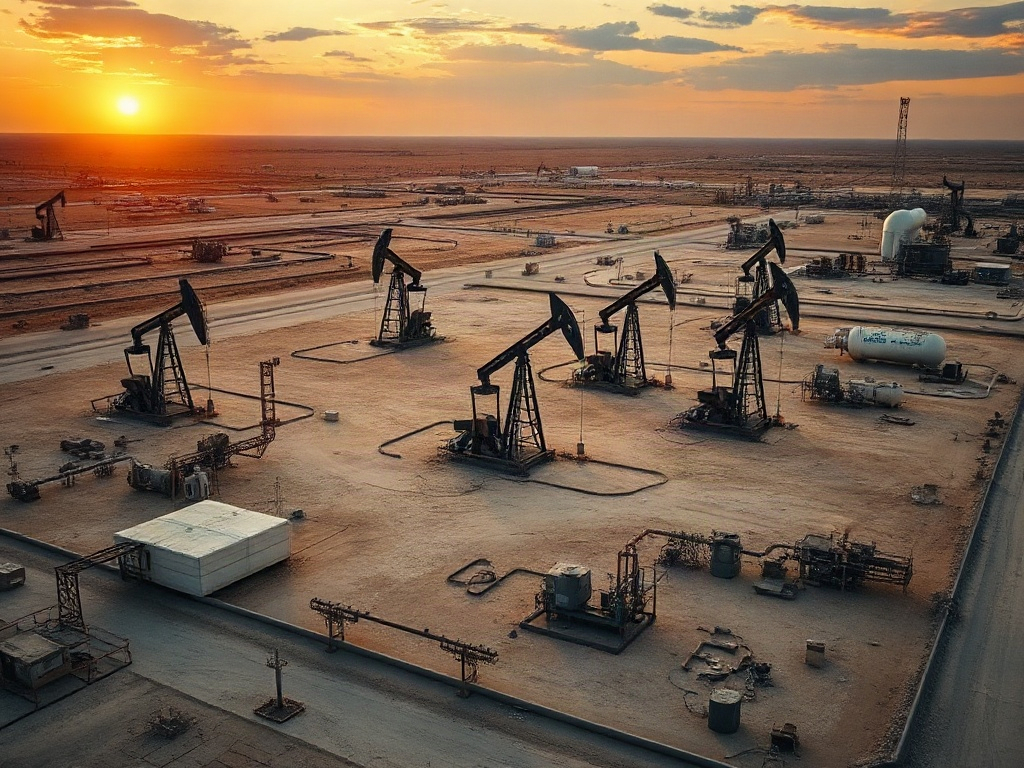
The Houston-based company announced in November 2026 the completion of a pilot at a naturally fractured carbonate reservoir in West Texas. Over thirty consecutive days it generated hydrogen through a subsurface bio-stimulation process: it injected a proprietary mixture of microorganisms into one well on the field, the microorganisms metabolized the residual oil trapped in the rock, and the hydrogen produced migrated through the reservoir until it was recovered in a second well located roughly 180 meters away. The gases produced were processed at the field's existing facilities and sold alongside natural gas. The pilot followed an earlier, smaller-scale test in California in 2025, but according to the company itself, the geological and chemical conditions of the Permian represented a significantly greater technical challenge.
Weatherford International provided operational field support. An energy engineering consultancy prepared the scaled-up cost projection. Those two names are not decorative: they signal that Eclipse built technical and industrial support before going public with its results.
The Hidden Asset in Dying Fields
Eclipse's business architecture rests on a premise that the petroleum sector knows well but has rarely managed to monetize in any other way: mature fields contain approximately 60% of the original oil in place that could never be economically extracted. That residual hydrocarbon did not disappear. It is still there, trapped in the rock, inaccessible to conventional production technologies. For Eclipse, that inventory is not a geological problem. It is a raw material.
The company's CEO, Prabhdeep Singh Sekhon, comes from the oil and gas industry. That matters because Eclipse's model does not require convincing operators of mature fields to abandon what they know. It offers them something different: converting an asset that is turning into a liability into an extended revenue stream lasting between ten and twenty years. The wells are already drilled. The surface facilities are already installed. The rights of way and gas gathering systems already exist. The capital sunk into that infrastructure was disbursed years ago by another party. Eclipse does not have to pay for it; it only has to use it.
That cost architecture goes a long way toward explaining the $0.56 per kilogram projection. It is not that the biological process is intrinsically cheap. It is that the model transfers a large share of capital costs onto assets that are already fully depreciated on another company's books. The question that logic raises is not whether the number is tempting. The question is whether the value transfer between Eclipse and the operators of mature fields can be structured so that both parties capture enough margin to justify the project.
Depinder Sandhu, Executive Vice President and Chief Commercial Officer at Weatherford, stated publicly that the technology makes it possible to convert a future abandonment cost into present income. That phrase describes exactly the fit between Eclipse and its target segment: operators who, without this alternative, would have to absorb plugging and environmental compliance costs with no offsetting cash flow. For those operators, the adoption threshold is conceptually low. The obstacle is not primarily economic. It is regulatory and technical.
Where the Pilot Ends and Where the Business Model Begins
Thirty days of continuous hydrogen production in the Permian is a result that deserves attention. It is also precisely the point at which an honest analysis must pause to separate what the pilot demonstrated from what it has not yet demonstrated.
The pilot established that the microorganisms can generate hydrogen under demanding geological and chemical conditions, that the hydrogen can migrate through the reservoir to an offset well, and that production can be sustained continuously for at least one month. That is no small thing. For a process that combines microbiology, reservoir engineering, and field gas logistics, thirty days of uninterrupted operation carries genuine technical value.
What the pilot did not establish is equally relevant to any structural analysis of the model. No daily production volumes were published. No verified carbon intensity figure was delivered that would allow one to determine whether the hydrogen produced meets the thresholds that would classify it as "clean" under existing regulatory frameworks. The bio-stimulation process also generates carbon dioxide; Eclipse notes that some of that CO₂ remains underground and that emissions can be captured, but without a verified capture rate and without a complete life-cycle analysis, the "clean" label remains a pending claim rather than an established fact.
Geoffrey Ellis, a researcher who studied geological hydrogen at the United States Geological Survey and is currently at Stanford University, acknowledged the enormous potential of the resource while also warning that scaling the technology could be difficult. That tension between resource potential and the complexity of scaling is precisely the structural knot Eclipse will have to untangle before the cost projection moves from being an engineering estimate to an operational result.
The path to that scale-up has at least four conditioning factors that will not be resolved simultaneously. First, production stability: it is one thing for the microorganisms to generate hydrogen for thirty days; it is another for them to do so at predictable flow rates for ten or twenty years as the hydrocarbon feedstock in the reservoir is gradually depleted. Second, geological portability: the pilot took place in a naturally fractured carbonate in the Permian. The characteristics of that reservoir are not universal. Each mature field will have its own temperature, pressure, salinity, and initial microbial composition profile, and there is no guarantee that Eclipse's proprietary microorganism blend will produce the same results under different conditions. Third, the regulatory framework: Sandhu noted that the technology works best in wells that have not yet been plugged, which creates time pressure and a need for legal certainty about the conversion of oil wells into hydrogen production facilities. Fourth, carbon accounting: if the carbon dioxide generated underground is not captured with verifiable permanence, the emissions profile of the process could complicate access to energy policy incentives that are currently tied to the carbon intensity of the hydrogen produced.
The Market Eclipse Is Choosing to Serve, and the One It Is Leaving Out
One of the most revealing signals about the structural maturity of an emerging model is the clarity with which it chooses its initial segment. Eclipse, according to its CEO's statements, is evaluating applications in industrial heat, heavy transport, chemical feedstocks, and power generation. It is also forming alliances with data center developers seeking firm energy sources located close to their facilities.
That range is broad. Too broad to be a signal of mature positioning. At this stage, it looks more like a demonstration that the potential market exists across multiple sectors than a clear decision about which of those sectors can absorb hydrogen at commercial scale within the two-to-three-year horizon Eclipse has set for its first commercial project.
The cleanest case for Eclipse does not necessarily lie in competing head-on with green hydrogen in long-established industrial applications. It lies in a more specific segment: operators of mature fields with wells that have not yet been plugged, that are close to existing gas infrastructure, and that have visibility into future abandonment costs. For that segment, Eclipse is not competing with green hydrogen or with blue hydrogen. It is competing with the cost of doing nothing with an asset that is turning into an obligation.
That distinction changes the competitive geometry entirely. The $0.56 per kilogram price does not need to be verified for a mature-field operator to find the conversation attractive. The entry threshold is lower than for an industrial hydrogen buyer that already has established options. And that suggests that the path to the first commercial project could be shorter than it appears if Eclipse concentrates its resources on that segment instead of dispersing them across five simultaneous markets.
Concentration would also resolve something that the current dispersion does not: the need to demonstrate sustained production, verified carbon intensity, and project economics to a single type of customer, under repeatable conditions, before attempting to serve all the others. Business models that try to validate multiple segments simultaneously generally end up without having validated any of them deeply enough to attract project capital at scale.
What the Pilot Reveals About the Current Moment in the Analysis
Eclipse Energy arrived at November 2026 with a technical result that deserves to be taken seriously and with an economic thesis that deserves to be examined with precision before being adopted. The pilot demonstrated that the process works under demanding conditions. It did not demonstrate that it works at commercial scale, that the carbon profile meets current regulatory standards, or that the cost projection survives the complexity of a ten-to-twenty-year project in reservoirs with characteristics different from those of the Permian.
That distance between what has already happened and what still has to happen does not invalidate the bet. It invalidates it only if it is confused with a promise already fulfilled. The two-to-three-year horizon toward a commercial project is ambitious but not unreasonable if the company manages to focus its validation strategy on the segment where the fit between proposition and customer is most direct. The combination of Weatherford as an operational partner and a substantial energy engineering consultancy as a technical validator gives Eclipse access to industrial credibility before it has commercial results. That is a strategic asset that few startups in this space possess at the same time.
What the analysis still cannot close with complete certainty is the most important question: whether reservoir biology can produce hydrogen with sufficient consistency, volume, and carbon intensity to make this a replicable model, or whether each mature field will present such different variables that the cost of characterization and project-by-project adjustment ends up eroding the cost advantage that makes the thesis attractive in the first place. That uncertainty is not a flaw in the model. It is the honest place where the analysis currently stands, and naming it with precision is more useful than forcing a conclusion that the available data does not yet support.